


Traders betting on a more dovish monetary policy and rate cuts from the European Central Bank may face disappointment if President Christine Lagarde pushes back against expectations for deeper easing than currently projected.
The euro is trading around $1.04, compared to a fair value of approximately $1.06 based on interest rate differentials. This largely reflects the risk premium from tariffs, and while risks of global trade disruption currently outweigh other factors, the ECB’s guidance will be crucial for the currency’s short-term dynamics.
A key factor could be comments on Trump’s economic policies, as Lagarde is likely to maintain flexibility and reiterate that the Governing Council remains data-dependent, making policy decisions on a meeting-by-meeting basis.
Positioning is significantly lighter than in early January but remains bearish, which creates risks of a short squeeze if short-term traders fail to find new catalysts for pushing the euro lower.
In the event of a rebound, options pricing suggests that January highs of $1.0533 will hold, at least on a closing basis, while a pullback is expected to find support around $1.0340-60.

Technically, the euro has broken out of the downward trend channel that began in late September, forming a short-term bullish crossover in moving averages (MA). However, as price action hovers around the 55-day MA, risks of false breakouts remain present.
For euro long positions, a decisive move above $1.0533 is needed to indicate a shift in sentiment. This would be further confirmed by a sustained push above $1.0572, which corresponds to the 38.2% Fibonacci retracement level of the September decline.
For euro sellers, the key focus will be on challenging support levels, defined by the 21-day MA and the January 21 low.

Overnight Volatility and Market Reactions Post-ECB Decision
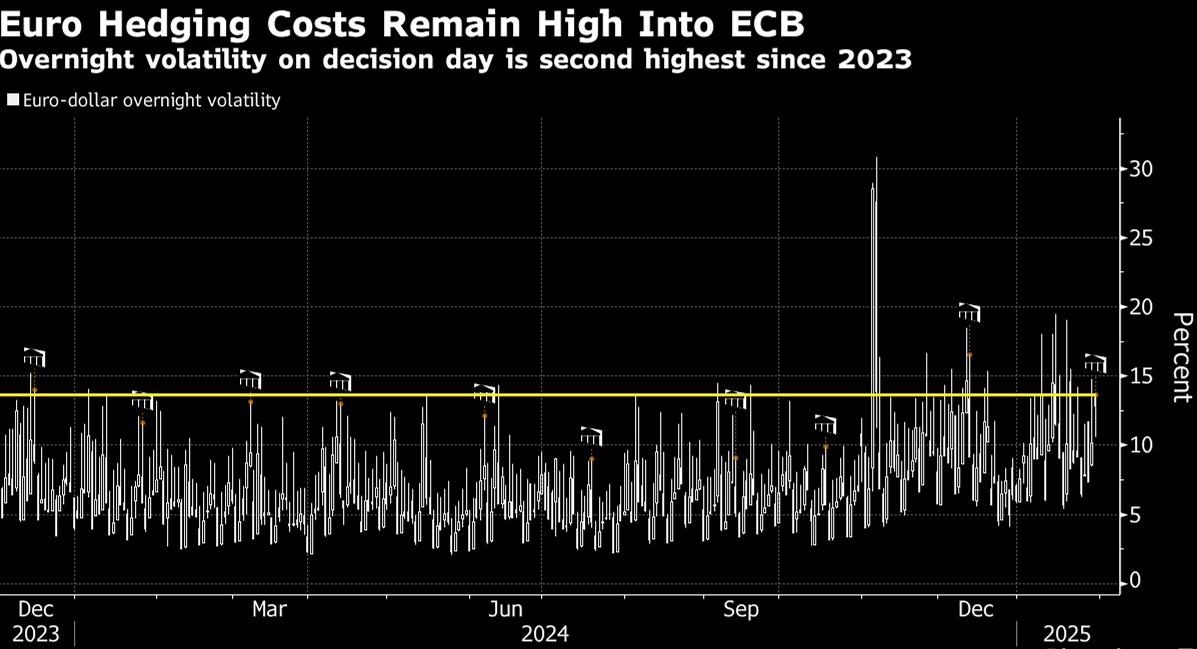
- Overnight volatility is trading near 12%, with a neutral value around 65 pips.
- One-week 25d risk reversals are trading at 27 basis points, with puts being priced higher than calls. Puts are being sold at a premium across all maturities, with the premium expanding the further out the option’s expiry date.
- Large options expiring today include:
- 1.0350-1.0355 (€3.04 billion)
- 1.0400 (€914 million)
- 1.0460-1.0470 (€1.25 billion)
- These large expiries will roll over into Friday at 1.0400 and 1.0450.
- Interbank desks are anticipating a rise to sell, ideally near 1.0500, while leveraged desks are maintaining small short positions, ready to stop selling below 1.0380.
- Major unfilled offers are visible around 1.0600.
ECB’s Impact on Euro and German Bonds
- Words from the ECB will likely hold more weight than actions today. Euro and German bond markets are expected to react moderately to the European Central Bank’s policy review. With the anticipated interest rate cut already priced in, market reaction will depend on whether the ECB alters its tone regarding its intentions.
- The 25 basis points cut to the deposit rate is largely priced in, and if the ECB matches market expectations, its main refinancing rate will be at 2.50% by the end of Q1. This is near the upper end of the neutral rate range, based on comments from several governing council members.
- The neutral rate in the eurozone is viewed at approximately 2.45%, which is why markets are particularly interested in whether the ECB will slow the pace of cuts after Q2.
- Last month’s guidance was as follows:”The Governing Council will follow a data-dependent, meeting-by-meeting approach to determine the appropriate monetary policy. In particular, decisions on interest rates will be based on its assessment of the inflation outlook in light of incoming economic and financial data, core inflation dynamics, and the strength of monetary policy transmission. The Governing Council does not pre-commit to a specific path for interest rates.”
- If the ECB changes its rhetoric to signal that future decisions will not follow an automatic path, it would indicate tightening, which would surprise the market. This is unlikely to happen before March when updated macroeconomic forecasts are available.
- Volatility estimates suggest that the euro could fluctuate by up to 0.67% against the dollar (spot reference value: $1.0420) in either direction following the ECB meeting. However, volatility may be lower if there is no dramatic shift in language from the ECB.
Varchev Absolute Trader
борсова платформа
- Търгувай над 3000 финансови инструмента: Crypto, Форекс, Акции, Индекси, Суровини, ETF-и
- Използвай платформа с директно изпращане ордерите на борсите
- Cloud base платформа - твоят трейдинг сетъп на всяко устройство
- Market Sentiment - търгувай с настроенията на инвестиционите банки
- Top movers - най-горещите трейдове във всеки един момент
- Stocks scanner - филтрирай най-подходящите за твоя трейдинг стил пазарни инструменти
- Heat map - Търгувай в посоката на големите играчи
Meta Trader 5
- Търгувай Crypto, Форекс, Акции, Индекси, Суровини - всичко на едно място
- Автоматизирана търговия с интелигентни стратегии и роботи (Expert Advisors)
- Разширен технически анализ с хиляди индикатора и инструменти
- Сигурност и стабилност – платформа, доверена от милиони по света
- Нулев марджин при насрещни/хеджирани позиции
- Без комисиона при търговия със CFDs
- Светкавично изпълнение на сделките
Read more:

Login to comment
Comments:
Leave a comment