


With no clear major seller in the market, the main bullish trend in gold is likely to remain intact for now, although a correction is possible as the metal is heavily overbought.
- Gold’s rally looks crazy — and it could get even wilder. That’s a bold statement after a relentless surge that has seen the precious metal more than double in just two years. Yet its main buyers still don’t seem ready to turn into sellers large enough to seriously threaten the bullish trend.
- As impressive as gold’s rise has been, it’s still not as explosive as the rally in the late 1970s, when the metal quadrupled in just over a year. Silver’s move back then was even more extreme.
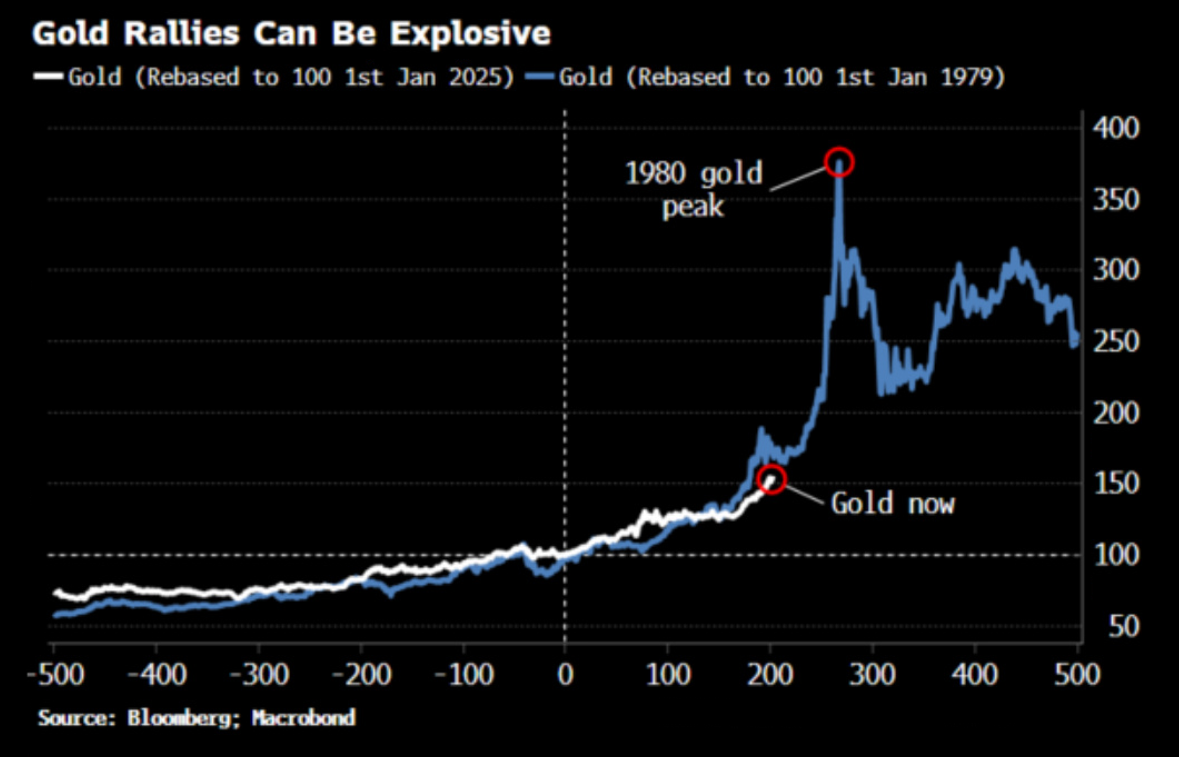
- During regime shifts, like today’s scenario when the U.S. renegotiates the terms of the Pax Americana, assets can exceed what most people expect. How far gold (and other precious metals) can rise requires an open mind, even if corrections are likely during periods when gold becomes overbought (as it is now).
- To reverse the rally, we would need to see a significant gold seller. But looking at the holders, there is no obvious candidate.
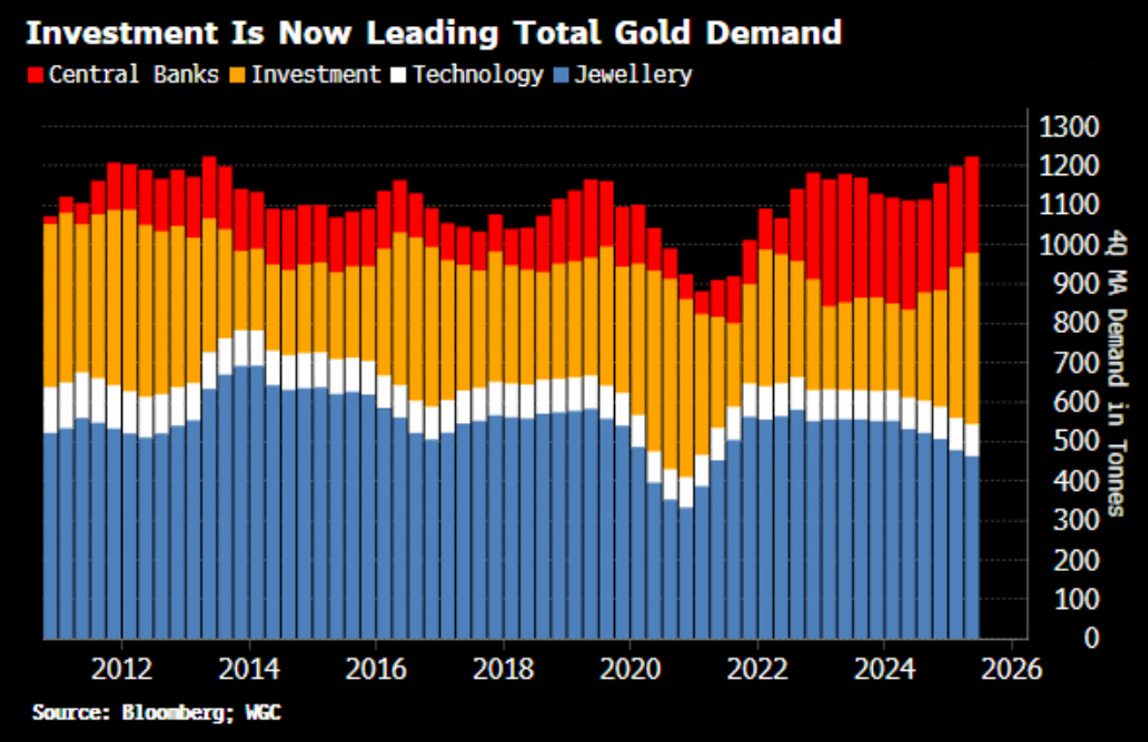
- Most purchases come from central banks, investments (ETFs, bars, coins, etc.), technology (electronics, dentistry, etc.), and jewelry.
- Only jewelry demand has declined in recent years. This is not unusual: it is generally negatively correlated with the price of gold, as high prices restrain demand. However, this decline is more than offset by increased demand from central banks and private investors. The fate of gold depends on these more price-sensitive buyers.
- Will they soon become sellers? Willem Buiter, a former member of the Bank of England’s Monetary Policy Committee and now special economic adviser at Citigroup, advised last week that central banks should do so. They have been the main drivers of the rally so far; however, there is no clear reason for them to start selling now.
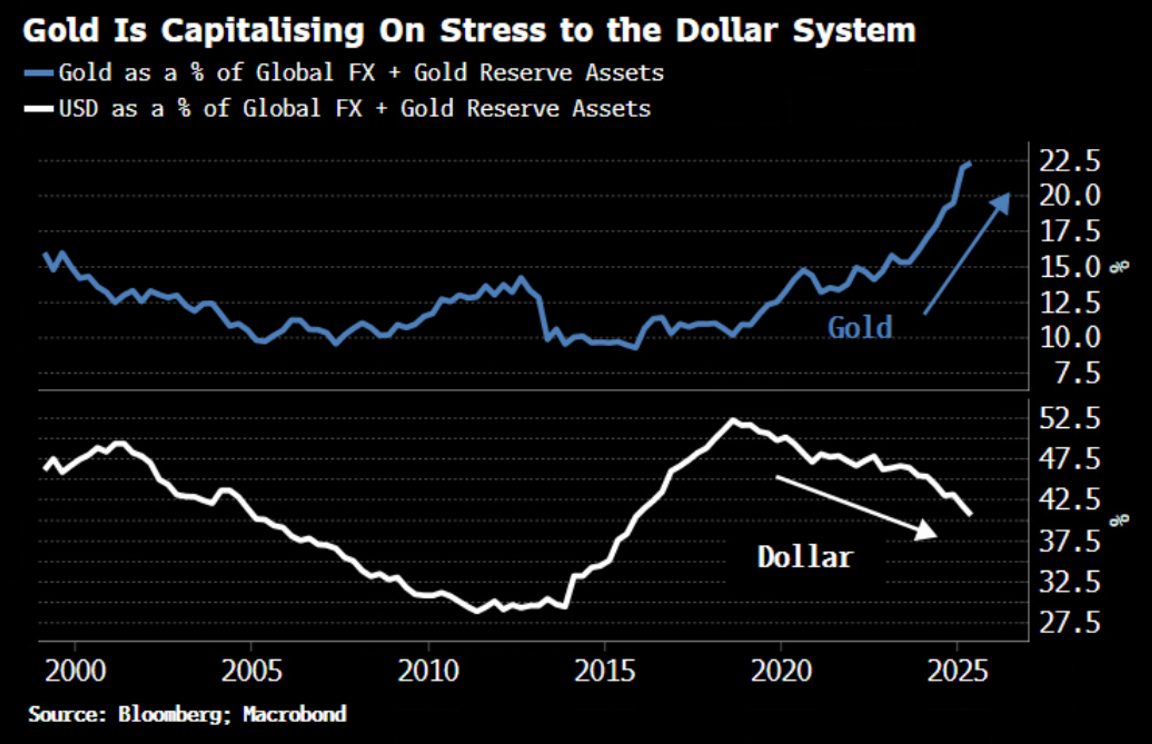
- The pandemic, the seizure of Russian reserve assets, and the trade war have led to a radical global rethink of the degree of exposure to the dollar, resulting in increased gold reserves and a reduction in dollar-denominated ones.
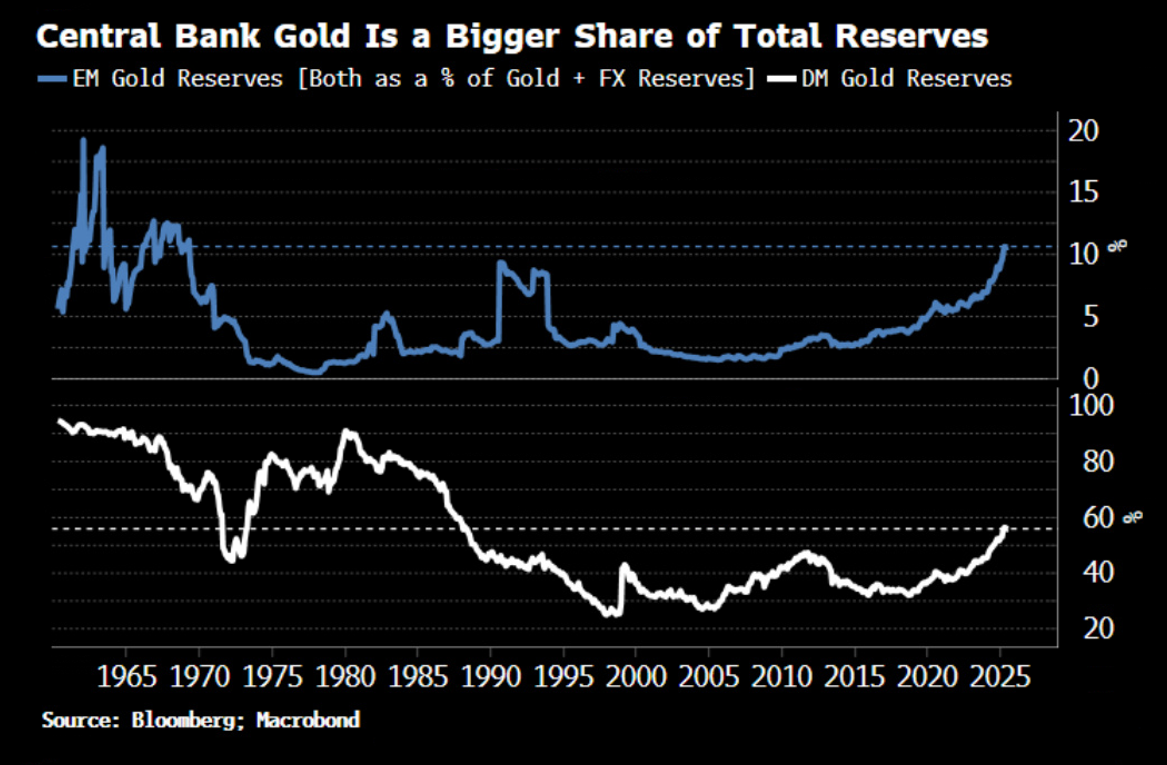
- Central bank purchases come entirely from emerging markets, as they are the most exposed to U.S. influence on the dollar. Developed-market banks have been net sellers of gold since the 1970s.
- Purchases from emerging markets have driven their banks’ gold reserves as a percentage of total reserves to peaks not seen since the early 1970s (when overall reserves were very low), while gold reserves in developed-market banks have reached 40-year highs, entirely due to valuation effects.
- But this does not mean that central banks are about to hit the sell button. First, emerging-market banks have only recently begun increasing their holdings, doing so to diversify away from the dollar. It is not obvious why they would change course so quickly or what they would buy instead.
- Second, central bank gold in developed countries as a percentage of reserves is higher than in emerging markets, since developed banks typically hold relatively few reserves. Yet it is also unclear why they would suddenly become major sellers now. No large emerging-market central bank has sold gold since the last significant rally ended in 2011. Moreover, even developed countries may still seek additional protection from a dollar weaponized as a geopolitical tool.
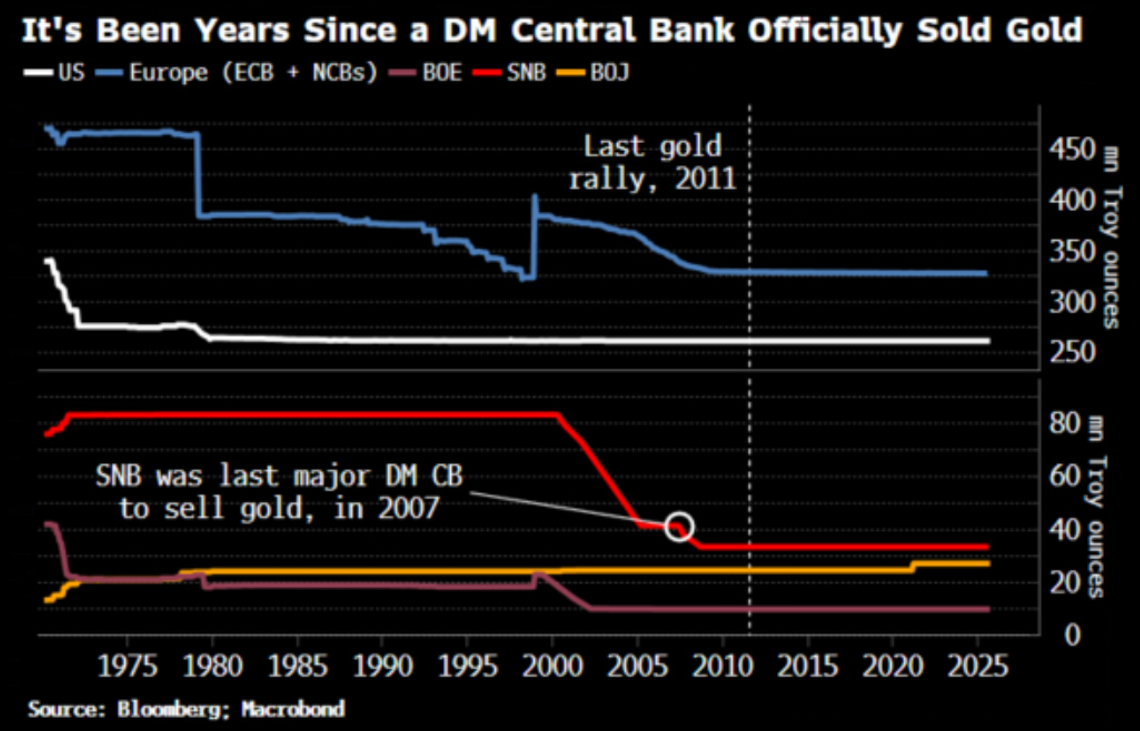
- Rumors of central bank sales contributed to the gold sell-off in 2011. It is possible that we will start hearing similar rumors soon, but since major developed central banks have not traded gold for decades, there is no compelling reason for them to start now.
- This is doubly true when looking at gold reserves relative to central bank assets (noting that in the case of the U.S., their gold is actually not on the Federal Reserve’s balance sheet). This ratio for developed markets is still below the level it was less than 20 years ago.
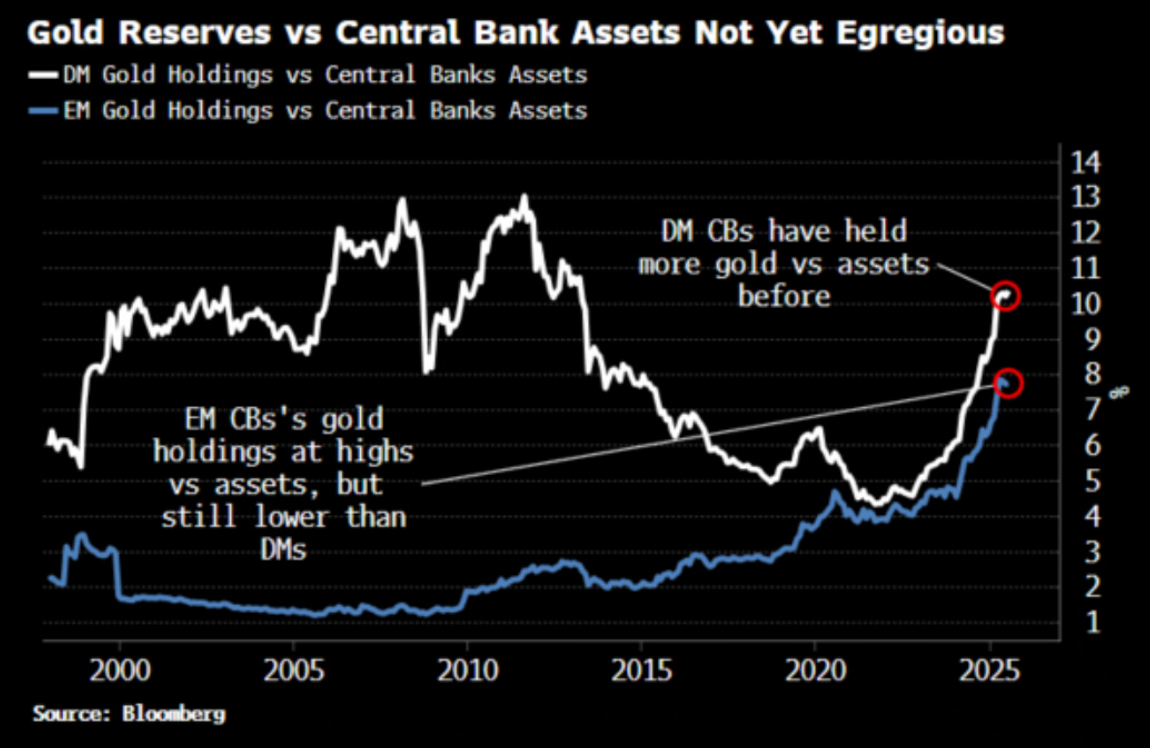
- The ratio for emerging markets is at a 25-year high, but it has risen from a very low base and is still lower than that of developed markets. Overall, therefore, there is no prima facie reason why developed or emerging countries would suddenly start selling their gold in volumes large enough to move the market.
- What about private investors? One of the largest vehicles for gold investment is ETFs. Using the largest such ETF—GLD—as a reference, we can see that investors only started increasing their purchases once the latest phase of the rally began in August. They are chasing the price.
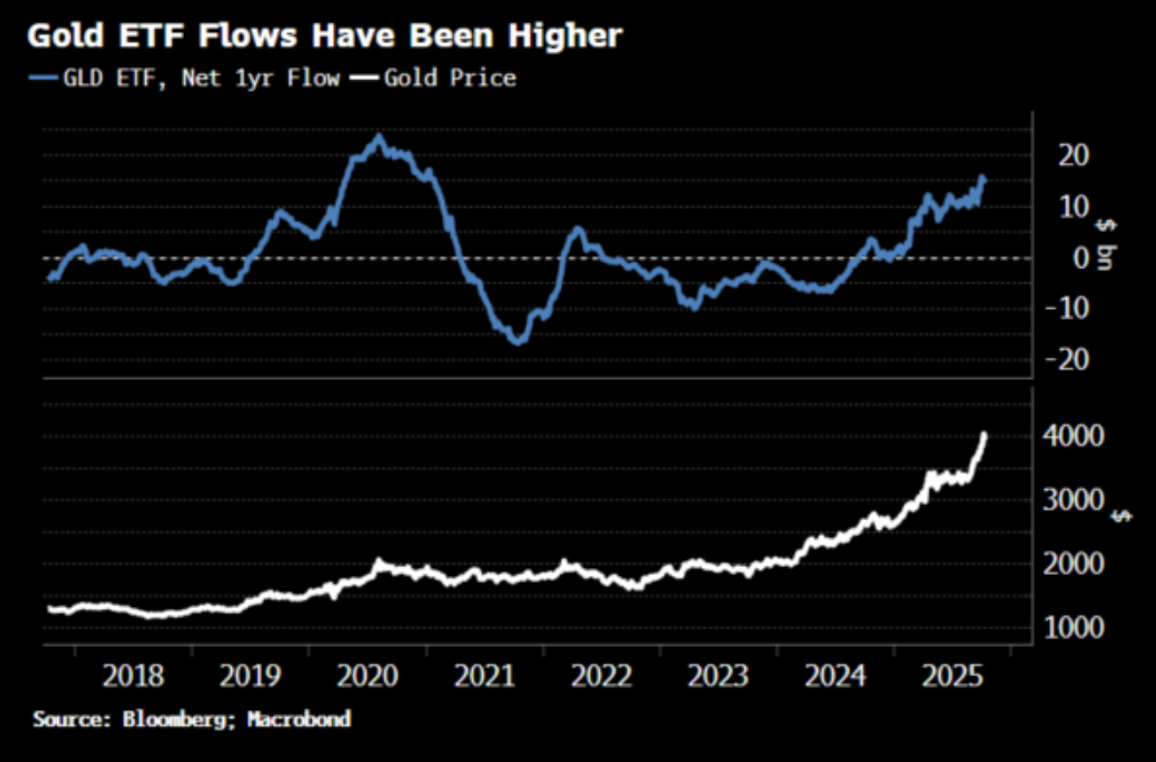
- Globally, we can see that shares in U.S. ETFs are increasing, but they are still below their recent peaks, while those in Europe also have room for further growth.
- Even more notable is the inflow into ETFs in Asia, driven mainly by China and India. It rose sharply since last year, paused in April, and is now rising again. Buyers in Asia are also beginning to chase higher prices.
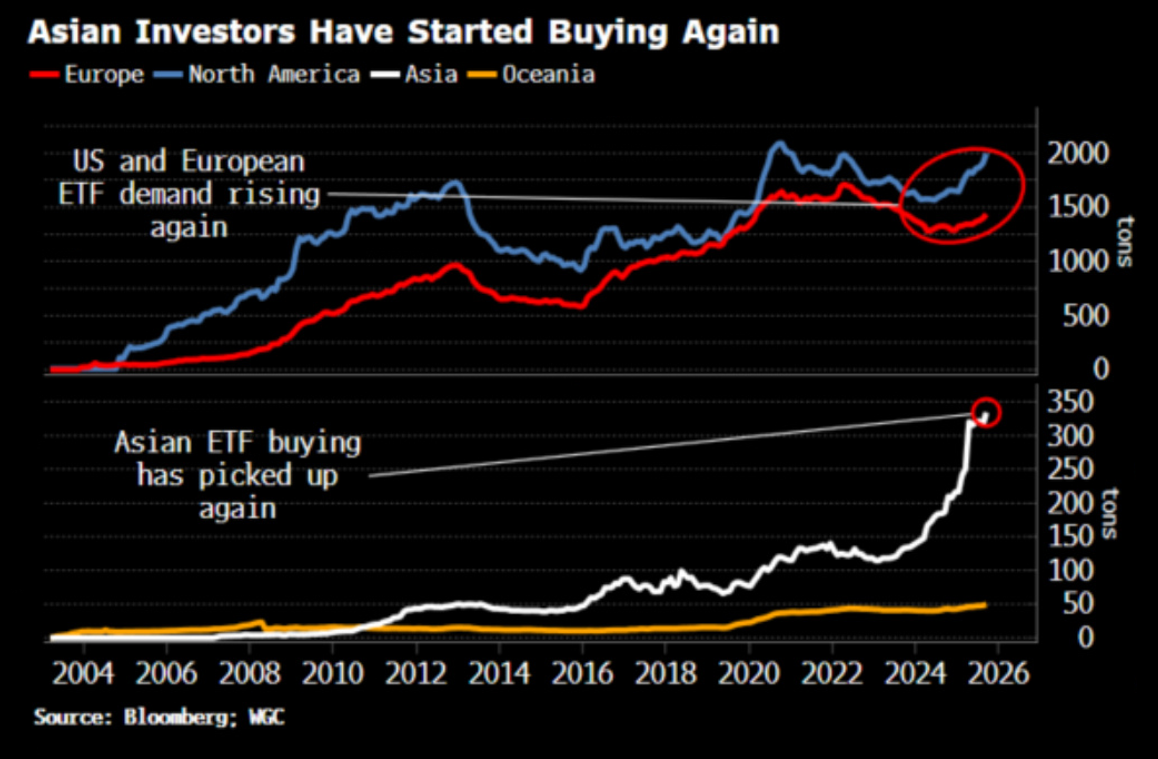
- Gold ETFs are a significant factor for demand from a cash flow perspective, even if they represent only about 1.5% of the shares invested in above-ground funds. They reflect overall investment demand, which accounts for over a fifth of the total shares.
- Speculators are long on gold, but they have been even longer in the past, with net long futures positions at the 80th percentile in Commitment of Traders data over the past 30 years.
- Rising gold prices and changes in the global macroeconomic environment may also prompt some investors to consider the precious metal—those who wouldn’t have given it a second thought just a few years ago. Morgan Stanley recommends that pension funds shift from a 60/40 equity/bond allocation to a 60/20/20 allocation with 20% in gold.
- Even this alone would represent a substantial source of new gold demand (and after a 100% price increase, it would come just in time for such “glacial” capital allocators).
- It doesn’t always take a big seller to stop a rally; sometimes simply running out of buyers is enough. But it appears we haven’t reached that point yet, and both real and speculative demand may continue to push gold higher.
 Head of Trading Dimitar Kalapov
Varchev Absolute Trader
борсова платформа
- Търгувай над 3000 финансови инструмента: Crypto, Форекс, Акции, Индекси, Суровини, ETF-и
- Използвай платформа с директно изпращане ордерите на борсите
- Cloud base платформа - твоят трейдинг сетъп на всяко устройство
- Market Sentiment - търгувай с настроенията на инвестиционите банки
- Top movers - най-горещите трейдове във всеки един момент
- Stocks scanner - филтрирай най-подходящите за твоя трейдинг стил пазарни инструменти
- Heat map - Търгувай в посоката на големите играчи
Отвори трейдинг сметка Опитай на демо
Meta Trader 5
- Търгувай Crypto, Форекс, Акции, Индекси, Суровини - всичко на едно място
- Автоматизирана търговия с интелигентни стратегии и роботи (Expert Advisors)
- Разширен технически анализ с хиляди индикатора и инструменти
- Сигурност и стабилност – платформа, доверена от милиони по света
- Нулев марджин при насрещни/хеджирани позиции
- Без комисиона при търговия със CFDs
- Светкавично изпълнение на сделките
Read more:

Login to comment
Comments:
Leave a comment