


- Dollar bulls appear strong in the first quarter, but don’t rely on this outlook: Currency forecast.
(Bloomberg Intelligence) – Cyclical and income factors are likely to once again be the main drivers of currency markets in 2026, but that doesn’t mean structural factors such as fiscal and debt dynamics can be ignored. The dollar may start the year strong, as the period following the end of the government shutdown will support positive economic headlines, but there is a risk that the market could fall victim to overly optimistic expectations for U.S. growth. Europe’s economy may also improve, opening an upward path for the euro as 2026 progresses.
The yen and the pound remain exposed to risk as fiscal threats persist, and we once again prefer defensive currencies such as the Swiss franc. The Swedish krona and the Norwegian krone are attractive structural choices.
In emerging-market currencies, yield is returning as a key factor — but so is politics. The Mexican peso, South African rand, and Hungarian forint appear well-positioned, while a weakening dollar in the second half of the year could push the dollar–yuan pair back below 7.00.
(24.11.2025)
Key topics
G-10 FX”
2026: Dollar bears will need to be patient in the first quarter and focus on factors outside the United States.
Identifying the key drivers for G-10 currencies in 2026 — the economy, inflation, and interest rates — is the easier part. The harder part is assessing how exactly they will evolve, especially in the United States, which implies low confidence in the dollar forecast at the start of the year. Nevertheless, an upward bias in the first quarter may emerge if there is confirmation of an economic rebound following the end of the government shutdown.
An expanding European economy and the ECB’s more advanced policy cycle could provide moderate support for the euro in 2026, while defensive currencies remain attractive at a time when the outlook for the yen is improving and the Swiss franc has a clearer upward path.
2. Dollar bears face a volatile first quarter but may return in 2026.
The U.S. government shutdown and the lack of economic data make it nearly impossible to accurately assess short-term cyclical dynamics. Therefore, caution will be needed when interpreting new economic releases. Nonetheless, the reopening of the government could lead to an improvement in economic data during the first quarter, which would support the dollar in early 2026.
We expect an improvement in cyclical indicators in the eurozone as previous fiscal stimulus measures begin to take effect and external demand recovers. This would provide moderate support for the euro as the year progresses.
Beyond the outlook for the dollar, given the highly uncertain global economic and political environment, we prefer defensive currencies such as the Swiss franc. We avoid the yen at the start of the first quarter and at least until fiscal-liquidity policy becomes clearer and tensions between China and Japan ease.
Key G-10 currency forecasts for 2026.
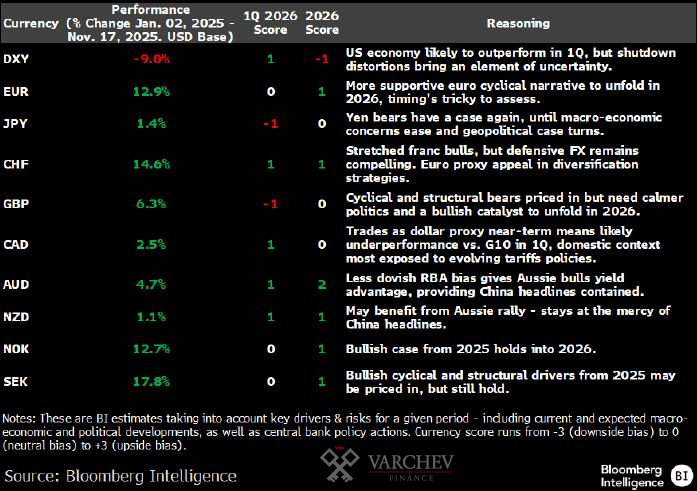
Identifying the key factors and risks for G-10 currencies in 2026.
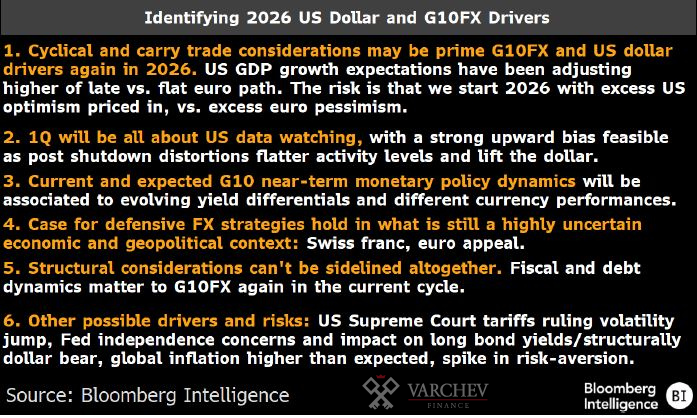
G-10 currencies have grown accustomed to operating in an environment of higher trade tariffs, and while this does not mean that structural factors fade into the background, we believe that cyclical and monetary-policy conditions will once again be the most significant drivers in 2026. This implies a return to closely monitoring U.S. economic growth and inflation data from the very beginning of the first quarter, even though distortions following the government shutdown will make assessing the economy more difficult.
Some relief may finally emerge in eurozone data, as Germany’s fiscal plans begin to have an impact on the economy in 2026. This aligns with a relatively constructive outlook for the euro against the dollar — supporting a scenario for a test of the $1.20 level — while dollar–yen bears from 2025 are likely to remain under pressure until the combination of fiscal and monetary policy in Japan becomes clearer and tensions between China and Japan ease.
There are also arguments supporting the continuation of a defensive currency strategy in 2025, with the Swiss franc being in the best position.
(19.11.2025)
Growth and yield are driving forces, but structural factors should not be forgotten.
- The U.S. dollar: Can America’s economic exceptionalism dominate in 2026?
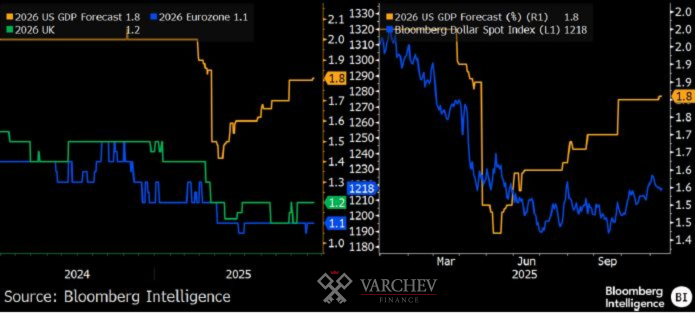
If you believe, as we do, that cyclical factors and yield will be the main drivers of G-10 currencies in 2026, the starting point is assessing U.S. economic performance (actual versus expected) and monitoring it relative to the economic and inflation expectations of other countries throughout the year. A rebound following the government shutdown, new fiscal stimulus, and previous easing could boost GDP in the first quarter, supporting dollar bulls. But as the year progresses, this influence will fade and attention will shift toward the improving economic environment in the eurozone.
As of November 14, the consensus shows that the U.S. GDP forecast for 2026 is 1.8%, up from the low 1.4% in May, with the possibility of upward revisions in early 2026 if the post-shutdown rebound in the first quarter is stronger than expected.
This contrasts with the consensus for the eurozone and the United Kingdom for 2026, which is trending downward and currently stands at 1.1% and 1.2%, respectively.
Tracking economic data will drive the dollar in 2026.
- Доларът на САЩ: Инфлацията и наративът на Федералния резерв
It is clear from the Fed’s latest communication that a weakening labor market will be the trigger for a potential rate cut toward a neutral level in 2026. Inflation and inflation expectations have so far had a smaller impact on the rate outlook, but any significant rise in U.S. prices in 2026 could become a relevant factor for the dollar.
In particular, if the Fed is perceived as having been too aggressive in cutting rates at a time when inflation remains stubborn and/or higher than expected, this could raise concerns about policy errors and/or the central bank’s independence. This would revive structural bearish sentiment toward the dollar through a higher risk premium at the long end of the yield curve.
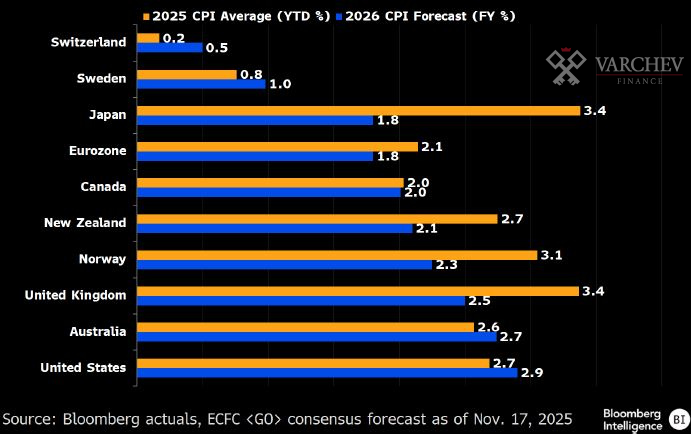
The global impact of tariffs on inflation has been smaller than expected in 2025, but there is a risk that it may materialize in 2026 (U.S. expected CPI inflation: 2.9% in 2026).
We still cannot forget about inflation.
- G-10 currencies: Everything may revolve around carry trades and yield differentials in 2026.
Carry trading means that current and expected yield differentials will shape currency market performance in 2026. Differences in short-term monetary policy expectations are a theme that dollar bears may rely on, although the Fed’s softer policy stance in 2026 is already partly priced in.
Still, Jerome Powell’s term at the Fed ends in May 2026, and it is easy to expect a more ‘dovish’ replacement, with our current assumption being a rate cut by the Fed toward the neutral level (around 3.25–3%).
In the G-10 currency space, the Fed is expected to cut rates the most, in contrast to a still-priced-in 50-basis-point hike by the BOJ (despite a recent hawkish adjustment).
The Bloomberg WIRP function, as of November 14, also shows 60 basis points of easing priced in for the BOE by October 2026, compared with a 6-basis-point hike for Norges Bank and an almost completed easing cycle by the ECB.
Expected yield scenario: bearish outlook for the dollar in 2026.
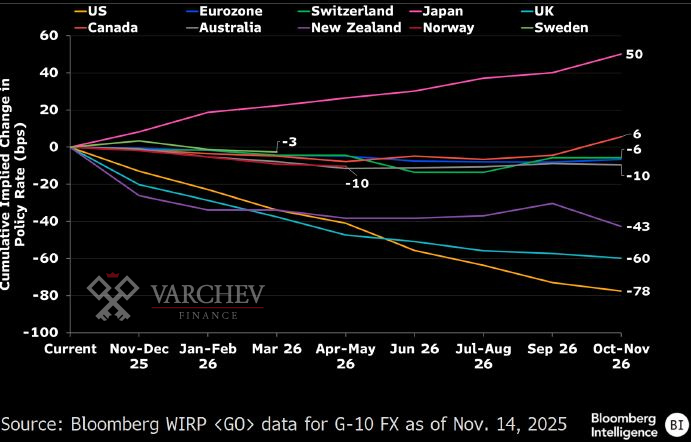
Източник: Bloomberg Intelligence
Varchev Absolute Trader
борсова платформа
- Търгувай над 3000 финансови инструмента: Crypto, Форекс, Акции, Индекси, Суровини, ETF-и
- Използвай платформа с директно изпращане ордерите на борсите
- Cloud base платформа - твоят трейдинг сетъп на всяко устройство
- Market Sentiment - търгувай с настроенията на инвестиционите банки
- Top movers - най-горещите трейдове във всеки един момент
- Stocks scanner - филтрирай най-подходящите за твоя трейдинг стил пазарни инструменти
- Heat map - Търгувай в посоката на големите играчи
Meta Trader 5
- Търгувай Crypto, Форекс, Акции, Индекси, Суровини - всичко на едно място
- Автоматизирана търговия с интелигентни стратегии и роботи (Expert Advisors)
- Разширен технически анализ с хиляди индикатора и инструменти
- Сигурност и стабилност – платформа, доверена от милиони по света
- Нулев марджин при насрещни/хеджирани позиции
- Без комисиона при търговия със CFDs
- Светкавично изпълнение на сделките
Read more:

Login to comment
Comments:
Leave a comment